U.S. Refining Capacity Just Hit a Decade Low, and the Product Map Is Redrawing
The National Picture: Capacity Falls to Its Lowest Level Since 2016
U.S. operable refinery capacity stood at 18.2 million barrels per calendar day as of January 1, 2026, down more than 250,000 b/cd, about 1%, from the prior year, and down to its lowest level since May 2016. The 130 operable refineries now running are two fewer than in 2025, following LyondellBasell’s exit from its 263,776-b/cd Houston refinery in March 2025 and Phillips 66’s shutdown of its 138,700-b/cd Los Angeles complex that October. Combined, those two closures removed roughly 400,000 b/d of capacity, only partially offset by minor efficiency gains elsewhere in the network.
California Bears the Brunt
Regional exposure to these closures varies sharply, and California is absorbing the worst of it. The Phillips 66 Los Angeles complex and Valero’s 145,000-b/d Benicia refinery, which ceased operations in February 2026, together represent about 17% of the state’s in-state refining capacity, a gap of roughly 306,000 b/d that must now be filled through imports. Stillwater Associates projects the Benicia closure alone will cut West Coast production by 9% for gasoline, 5% for diesel, and 3% for jet fuel. Diesel is the softest hit because renewable diesel already supplies about 70% of California’s diesel pool, but gasoline has no equivalent cushion: the state’s gasoline import share is on track to climb from roughly 8% of supply to as much as 17%.
Inventories Are Heading to 25-Year Lows
The EIA’s Short-Term Energy Outlook projects that combined U.S. inventories of gasoline, distillate, and jet fuel will fall to their lowest levels since 2000, ending 2026 at roughly 375 million barrels, just above the 358-million-barrel low set that year. The agency attributes the decline directly to the pending closures layered on top of steadily rising consumption, a combination that leaves less cushion nationwide to absorb any additional supply shock.
The Jones Act Bottleneck: Why California Can’t Just Import Its Way Out
California has no pipeline connection to Gulf Coast refining hubs, so marine transport is the only way to move product in. That should favor U.S. Gulf Coast suppliers, except the Jones Act requires that cargo moved between U.S. ports travel on U.S.-built, U.S.-flagged, U.S.-crewed vessels, and only 54 of the roughly 7,500 tankers in the world fleet qualify. A California Energy Commission analysis found that shipping gasoline in from Singapore, roughly 7,700 nautical miles away, can run about 60% cheaper than a compliant coastwise move from the Gulf Coast, which is why the state’s fuel buyers have historically looked to Asia rather than Texas or Louisiana.
The scale of the workaround is striking. To cool prices after the Iran conflict disrupted Middle Eastern supply, the White House waived the Jones Act for coastwise fuel movements starting in March 2026, extending it twice, most recently through mid-November. In the roughly three and a half months that followed, foreign-flagged tankers moved more gasoline into California than the state had received under any waiver in the prior fifteen years combined. Even so, the effect on prices was modest: California received over 60% of waiver cargoes, but that volume, about 2.1 million gallons a day, covers only 6% of the state’s daily consumption. A temporary legal exemption can redirect ships; it can’t manufacture new refining or pipeline capacity that doesn’t exist.
The Logistics Response: Terminals, Conversions, and New Pipeline Capacity
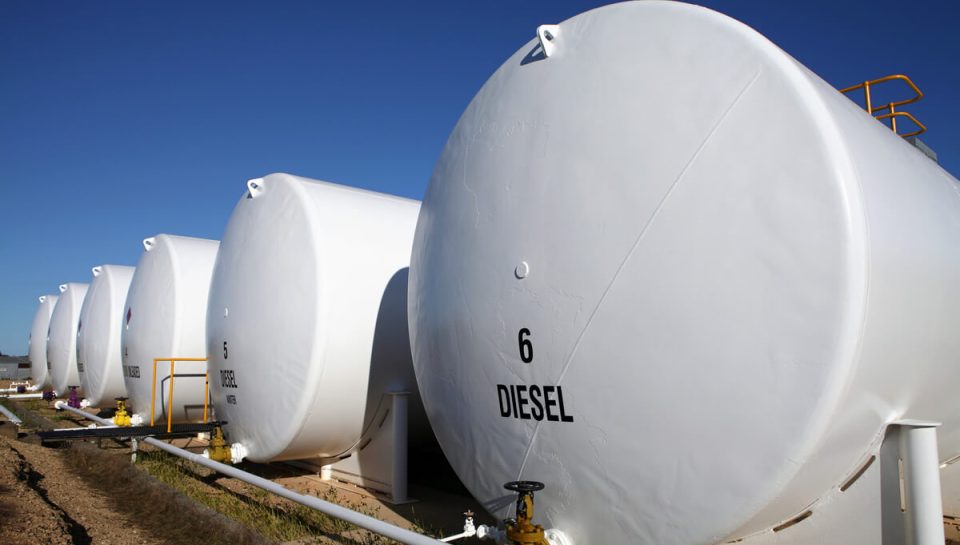
Midstream operators are responding on two fronts. Some are converting former refinery sites into pure storage and terminal assets, repurposing existing tanks, docks, and pipeline connections rather than building new infrastructure from scratch; Marathon’s Martinez and Phillips 66’s Rodeo facilities both converted crude storage into product storage as part of earlier renewable diesel transitions, a playbook now being studied more broadly. Others are betting on new cross-country pipeline capacity: Kinder Morgan and Phillips 66 closed their second open season in April 2026 for the proposed Western Gateway Pipeline, which would connect Midwest and Gulf Coast refined product supply to Phoenix and California markets, though it isn’t targeted for completion until mid-2029. In the meantime, Kinder Morgan is investing $139 million to expand refined products connectivity at its Houston Ship Channel hub, and Enterprise Products reported refined product marine terminal volumes at its Beaumont, Texas facility rising by more than 50,000 barrels per day quarter over quarter, evidence that Gulf Coast export infrastructure is already absorbing the redirected volume.
What This Means for Shippers and Investors
Refinery footprint decisions can no longer be evaluated on standalone economics; they have to be weighed against the region’s actual import infrastructure, including port capacity, available vessel classes, and, where applicable, Jones Act exposure. A market that loses conventional refining capacity but lacks the pipeline or marine capacity to backfill it structurally trades higher price volatility for lower supply reliability, and that risk shows up years before it shows up at the pump. Operators, investors, and shippers exposed to constrained regions should be underwriting logistics feasibility alongside refining economics, not after the closure is already announced.
Sources:
- U.S. Energy Information Administration
- California Energy Commission
- Stillwater Associates
- RBN Energy
- U.S. Maritime Administration